The European Union (EU) is governed by control-freak bureaucrats who hate anything that is not "harmonized" or "standardized" by EU regulations. The European common market, which was supposed to remove trade restrictions and increase market competition, has turned into a regulatory cage that creates oligopolies, drives economic inefficiency, and kills innovation.
The latest regulatory push targets offshore banking and could make it much more difficult for EU residents to access banking services from non-EU banks that do not have a branch in the relevant EU Member State. The rule will take effect on January 11, 2027. Our Hub Members already received a full breakdown of this news in an Emergency Briefing a few weeks ago.
The new directive has also been incorporated into the Agreement on the European Economic Area (EEA Agreement), which covers Iceland, Liechtenstein, and Norway. However, its entry into force remains pending the required notifications under Article 103(1) of the EEA Agreement.
The usual argument is that the rule keeps people safe by regulating banks and making sure they meet the standards required to do business in Europe. To me, it is a classic case of protectionism, one of the worst examples of economic paternalism, and, more importantly, an implicit, sneaky form of capital control aimed at keeping capital within the EU.
Under the new rule, even Swiss banks will be considered third-country institutions and, where Article 21c applies, will generally need an authorized branch in the relevant EU Member State to provide the covered services. Setting up licensed EU branches is slow, costly, and heavily regulated. Instead of complying, the most likely outcome is that many offshore institutions will simply stop onboarding EU residents altogether. Some banks have already begun closing their doors.
In this article, I will explain what the rule says, who it targets, and why permanently relocating outside the EU and changing your tax residence may be the only viable solution.
Under CRD VI, non-EU banks will generally need an authorized branch in the relevant EU country to provide residents with core banking services such as deposits, loans, and guarantees, although specific exemptions apply and certain lending by non-bank entities falls outside the restriction
THE BAN ON CORE BANKING SERVICES
The crackdown stems from EU Directive 2024/1619, commonly known as CRD VI (Capital Requirements Directive VI). This directive introduces a new Article 21c to the EU's banking framework, generally requiring banks established outside the EU to establish an authorized branch before providing covered banking services on a cross-border basis to clients established or situated in the EU.
Thus, subject to the exemptions in Article 21c, non-EU banks will be restricted from offering core banking services, such as taking deposits, lending money, and issuing guarantees, to EU residents. However, certain lending activities carried out by non-bank entities, including some private fund structures, fall outside the restriction.
HOW BANKS CLASSIFY EU RESIDENTS UNDER THE NEW RULE
The most critical detail about the rule is that it targets clients established or situated in the EU. Therefore, the key question is where you are situated, not the passport you carry. In practice, banks may use your residential address, tax residence, and other KYC information when making that determination.
For example, a French citizen who genuinely relocates to Dubai and is no longer situated in the EU would not be treated as an EU client merely because of their French citizenship, while a U.S. citizen living in Madrid would generally be situated in the EU.
However, if a foreign bank sees a French address on your application form, they will most likely treat you as situated or resident in the EU without undertaking a more detailed status assessment. Your nationality is not the determining factor in either scenario.
TWO PROVISIONS THAT MATTER MOST TO INDIVIDUAL OFFSHORE BANKING CLIENTS
Two provisions that seem especially important to individual offshore banking clients are:
-
Grandfathered Contracts: Existing contracts entered into before July 11, 2026, are grandfathered under the transitional provision, but the problem is that this deadline has already passed. If you do not already have an established offshore contract, this exception will not benefit you in any way.
-
"Reverse Solicitation": Technically, if an EU resident approaches a non-EU bank entirely on their own initiative, the bank is allowed to serve them. However, regulators have explicitly stated that this exemption will be interpreted very strictly. Banks are acutely aware of the compliance risks. Rather than painstakingly documenting that every single interaction was genuinely client-initiated, most compliance departments will find it easier to simply deny all EU residents.
THE REALITY OF OFFSHORE BANK ONBOARDING RIGHT NOW
If you reside in the EU, opening a bank account outside the bloc is going to become a massive headache from now on. The reality is that compliance departments are not waiting for 2027 to start de-risking. Because the regulatory burden and cost of establishing a fully licensed, capitalized branch in an EU member state is extraordinarily high, many offshore banks have simply decided that European retail clients are no longer worth the legal exposure.
As a result, the friction is already happening on the ground. If you attempt to open an offshore account today, you will likely encounter these new barriers:
-
Automated Rejections: Some banks are actively updating their KYC (Know Your Customer) software algorithms. An EU residential address, a European phone code, or an EU tax identification number may increasingly trigger an automatic block during the initial application phase.
-
Aggressive "Proof of Address" Checks: To prove you live outside the EU, they are heavily scrutinizing utility bills, long-term lease agreements, and local economic ties to ensure you have a genuine physical presence in your new country, rather than just a "paper" residency. Even that documentation may not be sufficient to convince the bank.
-
Preemptive Account Closures: Some institutions are already reviewing their portfolios and restricting services for clients with an EU footprint.
In short, providing an EU address or tax identification number with a banking application is no longer just a standard piece of information, but could rapidly become grounds for disqualification.
CRD VI will restrict EU residents’ access to core banking services from non-EU banks, making it harder to diversify assets internationally and maintain financial sovereignty
WHY THIS IS ALARMING
Any serious Plan-B requires jurisdictional diversification of your assets, and even this basic move demands that you use offshore banking services. Yet if you reside in the EU, even without an EU passport, new regulations make offshore banking really hard. That burden is too much for any serious international investor or expat who has built an international life abroad. This is not a trivial, bizarre EU regulation about the size and colour of fruits and vegetables. It directly targets your economic sovereignty by limiting your banking options.
This rule will hold your financial capital hostage, and from now on, if there is no serious reaction (I doubt there will be any), you will see continued increases in banking restrictions. The EU has entered into a vicious cycle where it eats up its own financial and human capital like there is no end. However, the end is pretty clear to me: a massive witch hunt will start against wealthy Europeans, if it hasn't already.
THE SOLUTION: MOVING OUTSIDE THE EU
Long before this absurd limitation on offshore banking, the EU was uninhabitable for anyone who cherishes their economic sovereignty. However, with this new rule, leaving the EU is imperative for anyone who considers financial freedom and access to offshore banking non-negotiable. Thus, the cleanest and only permanent solution to avoid this assault on your economic freedom is to move your tax residence out of the EU and EEA before control-freak regulators fully trap you.
Obtaining a secondary ‘paper’ residency in a tax haven while remaining tax-resident in an EU country means your account may still be subject to applicable financial-account reporting requirements. This implies that you may remain subject to the tax rules of the EU country where you are a tax resident, including, depending on the circumstances, taxation on your worldwide income. You must actually live and do business elsewhere.
Fortunately, there are excellent alternatives. Many jurisdictions, such as Panama, offer world-class offshore banking infrastructure paired with straightforward, welcoming residency programs.
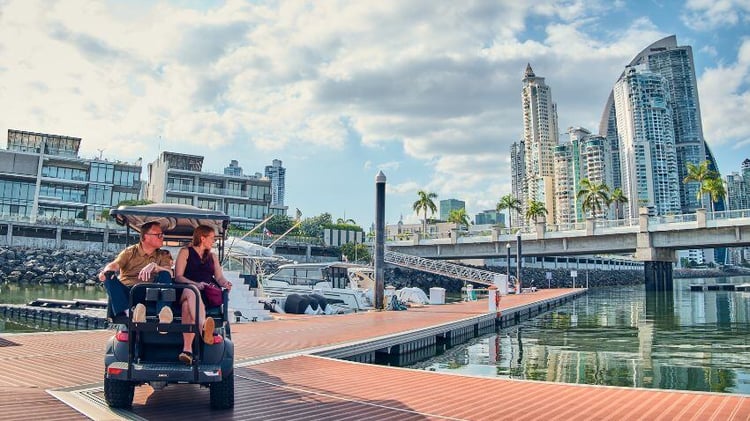
As regulations increasingly restrict your financial options, building a Plan-B in jurisdictions that welcome your capital and talent is one of the best ways to protect your banking freedom and economic sovereignty
CONCLUSION
The world has been dragged into a dark episode, and no one knows how the conflicts between global powers and even middle powers will unfold. The only thing you can do is to concentrate on the moves you still have control over. However, that circle of control has also been tightening, as politicians and bureaucrats are breathing down your neck to stop you from doing the right thing for yourself and the future of your family.
The best move is to stay away from heavy regulations that strangle your economic sovereignty by building your Plan-B, where your capital and talent are welcomed. If you are ready to protect your banking freedom, Expat Money can guide you through the process of securing offshore bank accounts.




 Mikkel Thorup: September 14, 2026